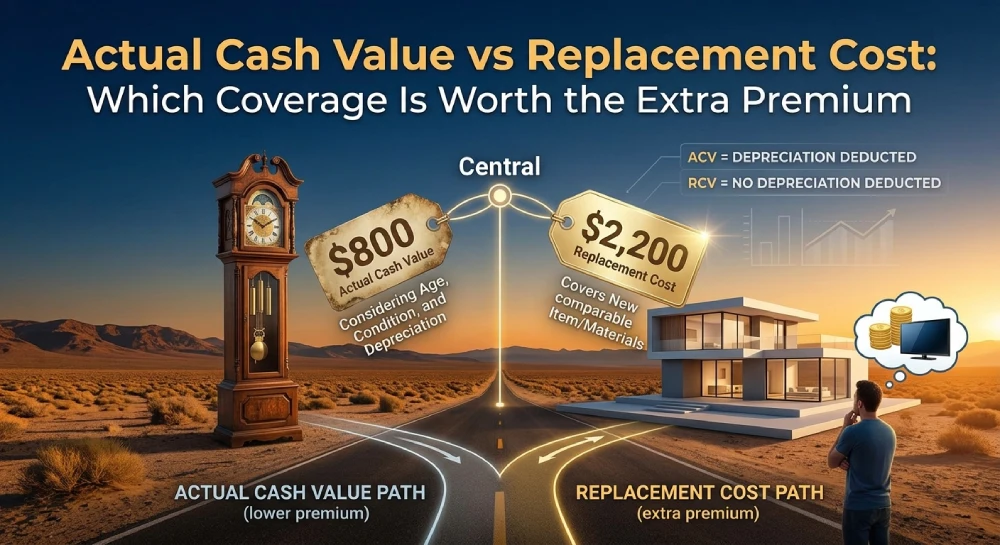
Choosing homeowners insurance involves more than comparing premiums. The amount an insurer pays after a covered loss can make a significant difference to a household budget. Understanding actual cash value vs replacement cost helps homeowners choose coverage that balances affordability with financial protection.
Actual cash value accounts for depreciation, while replacement cost generally covers eligible repair or replacement expenses without deducting depreciation. Both options have advantages, but the right choice depends on property value, savings, and insurance needs.
What Is Actual Cash Value Insurance?
Actual cash value insurance reimburses the actual value of the property at the time of the covered loss, considering depreciation due to age, condition and use. A friend buys a TV for $1,000 and after a few years it is worth $500. The insurance company may be liable to cover $500 without applying the deductible.
What Is Replacement Cost Value?
Replacement cost value represents the cost of repairing or replacing covered property with comparable materials or items without deducting depreciation in the same way as actual cash value coverage.
For instance, if a washing machine is damaged and needs replacing at $900, an eligible replacement cost claim might reimburse $900 (up to policy limits and conditions) before the deductible.
Replacement cost insurance may be especially useful in replacing large amounts of necessary property or if it’s necessary to rebuild a home in a way that will create financial pressure.
Actual Cash Value vs Replacement Cost: Key Differences
The primary difference is how depreciation affects the claim settlement.
| Feature | Actual Cash Value | Replacement Cost |
| Depreciation | Deducted | Generally not deducted from eligible replacement costs |
| Premium | Usually lower | Usually higher |
| Claim payout | Depreciated value | Eligible replacement expenses |
| Replacing belongings | More out-of-pocket costs possible | Greater financial assistance |
| Best for | Budget-conscious homeowners | Those seeking stronger protection |
Both policies remain subject to deductibles, exclusions, and coverage limits. Some policies also apply special settlement rules to roofs and other building components.
How Does Property Depreciation Affect Claims?
Property depreciation reduces an item’s estimated value as it ages or experiences wear and tear. Under actual cash value coverage, this reduction can significantly lower claim payments.
Consider a sofa with the following estimated values:
| Item | Amount |
| Original purchase price | $2,000 |
| Current depreciated value | $800 |
| Comparable replacement cost | $2,200 |
| Difference before deductible | $1,400 |
These are not actual numbers. The actual settlements will depend on the methodology employed in the valuation by the insurer, the condition of the item and the terms of the policy.
If the homeowner has actual cash value coverage, they could get around $800 before paying the deductible. Replacement cost coverage might be more useful for the $2,200 replacement.
Is Full Replacement Cost Coverage Worth the Extra Premium?
When homeowners cannot afford to pay the shortfall between a settlement and the cost to actually replace their home, full replacement cost coverage might be worth considering.
When replacement cost makes sense
- Expensive belongings:.Furniture, electronics and appliances are all expensive items that can be replaced.
- Limited savings: Higher claim payments may reduce financial pressure after a loss.
- Rising construction costs: The cost of repairs may go up with time.
- Long-term protection: Good coverage can help to deal with the unexpected repairs.
When actual cash value may work
- Lower premiums: Insurance with tight budgets may be more affordable.
- Older Items: If you have items that are older, some homeowners will take a discounted price.
- Strong Savings: Cash is available to cover replacement shortfalls.
Not all the cheapest policies are necessarily the most cost effective. Even if the premium saving is relatively small, it can be less than the out-of-pocket costs that can result from a large claim.
How to Choose the Right Homeowners Insurance Policy
The rebuilding costs and the value of household belongings should be reflected in a homeowners insurance policy that is suitable.
1. Estimate rebuilding costs
Re-building is not the same as market value. Reconstruction costs are based on the labor and material costs, demolition, and other eligible costs. Make sure that the dwelling’s value is in line with local construction costs.
2. Review home contents insurance
Verify furniture, clothing, appliances and electronics are protected by actual cash value versus replacement cost. A household inventory can help to determine coverage gaps.
3. Compare premiums and deductibles
Ask for similar coverage limits and deductibles, along with similar quotes. Otherwise, a lower-cost policy could just provide less coverage.
4. Consult an insurance agent
An insurance agent will explain the rules of depreciation, exclusions, replacement needs and special limits for valuable property.
Check to see if receipt is necessary, how recoverable depreciation works, if there is a policy that covers current rebuild costs.
Conclusion:
Deciding between actual cash value vs replacement cost coverage involves balancing premiums against coverage. While actual cash value might save money in the short term, depreciation can cost homeowners more after a loss.
Replacement cost coverage normally provides better protection against replacement costs. Those who are considering buying a home can make a wise choice by comparing equivalent policies and examining the settlement conditions.
Frequently Asked Questions
What is the main difference between actual cash value vs replacement cost?
Actual cash value deducts depreciation when calculating covered losses. Replacement cost generally pays eligible replacement expenses without the same depreciation deduction, subject to policy limits and conditions.
Is replacement cost insurance worth the extra premium?
It can be worthwhile when replacing damaged property would strain savings. Compare the additional premium with the potential out-of-pocket expenses after a significant loss.
What is actual cash value insurance?
It covers eligible property losses based on the item’s estimated value at the time of damage, accounting for depreciation, condition, and age.
What is replacement cost value?
Replacement cost value estimates the expense of repairing or replacing covered property with comparable materials or items, subject to policy requirements and limits.
How does depreciation affect insurance claims?
The actual cash value claim payments can be lowered by depreciation. Most of the time, replacement cost coverage will pay for replacement costs that are eligible (but not the same) without the deduction.
Can homeowners switch to replacement cost coverage?
Many insurers offer the option to change coverage subject to eligibility and approval. When switching, ensure you confirm with them the new premiums, coverage limits and date.
Does replacement cost cover the entire expense?
Not necessarily. Final payment may be affected by deductibles, exclusions, coverage limits and repair requirements.
Is market value the same as rebuilding cost?
No. Market value considers the land value and local market conditions, whereas rebuilding costs the expense of rebuilding the home.
Does home contents insurance include replacement cost?
This will depend on the policy. Discuss the terms, coverage and/or limits of personal property coverage.
How should homeowners choose the right coverage?
Look at the premiums, deductibles, replacement costs and claim settlement conditions. Pick the one that offers suitable protection without going over budget.