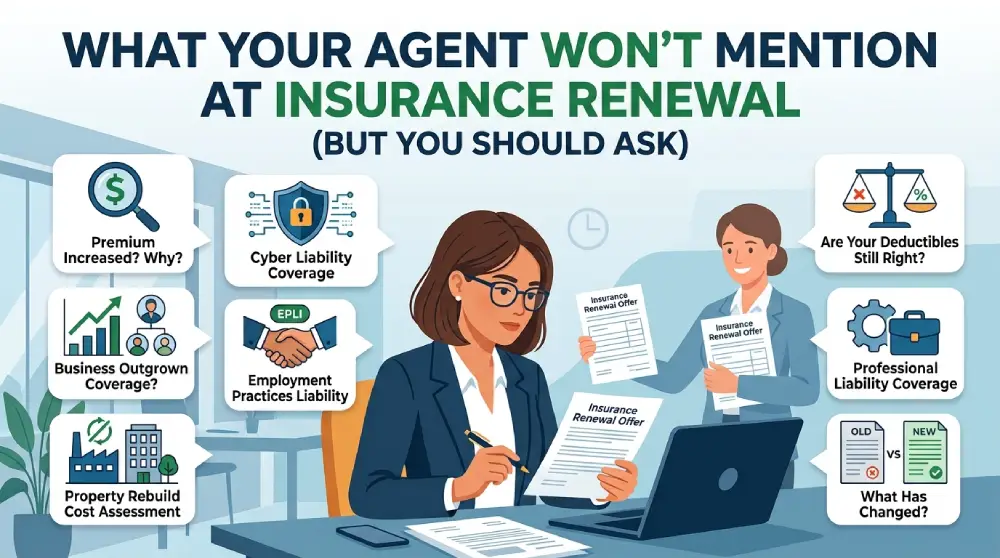
When your business insurance renewal arrives, it may seem easier to accept the updated premium and continue with the same coverage. However, renewing without reviewing your policy could mean paying more for protection that no longer meets your business needs.
An insurance renewal is an opportunity to review your risks, compare coverage, question price increases, and identify gaps before they become expensive problems.
Here are nine important things to discuss with your insurance agent before renewing.
1. Has Your Business Outgrown Its Current Coverage?
Your business may have changed since you purchased your original policy. You may have hired employees, purchased equipment, expanded operations, or introduced new services.
Your existing Business Insurance Policy should reflect these changes. Ask your agent whether your current limits still cover your property, equipment, inventory, and business activities.
2. Why Has Your Premium Increased?
Insurance premiums can rise even without a claim. Changes in the Insurance Market, inflation, repair costs, and industry-wide losses can affect pricing.
Ask your agent to explain which coverage costs increased, whether your risk classification changed, and if other insurers offer better rates.
3. How Can You Lower Business Insurance Costs?
You may be able to reduce premiums without sacrificing important protection.
Consider asking about:
- Discounts for workplace safety improvements.
- Bundling eligible commercial policies.
- Removing duplicate or unnecessary coverage.
- Comparing quotes from other insurers.
- Adjusting deductibles where affordable.
Understanding how to lower business insurance costs starts with reviewing what you’re paying for.
4. Are Your Insurance Deductibles Still Right?
A deductible is the amount your business pays before insurance covers an eligible claim.
A higher deductible may lower your premium, but it also increases your out-of-pocket expenses after a loss. Ask your agent to compare different options and choose an amount your business can comfortably afford.
5. Do You Need Cyber Liability Coverage?
Cyberattacks, ransomware, and data breaches can create significant financial problems.
Standard commercial insurance may not cover every cyber-related loss. Ask whether Cyber Liability coverage includes data recovery, breach notification, legal expenses, and certain business interruption losses.
Also review exclusions involving cybersecurity practices and outdated systems.
6. Does Your Policy Include Employment Practices Liability?
Businesses with employees face risks involving wrongful termination, discrimination, harassment, and retaliation claims.
Employment Practices Liability Insurance (EPLI) can help protect against certain employee-related lawsuits. Ask whether your policy includes this protection or requires a separate policy.
7. Is Your Professional Liability Coverage Enough?
Businesses providing consulting, advice, design, or specialized services may need professional liability insurance.
It generally covers certain claims involving professional mistakes or negligence. If your business handles sensitive customer information, ask whether professional liability insurance cyber coverage is included or needs to be purchased separately.
8. Have You Reviewed Your Rebuild Cost Assessment?
Property insurance should reflect what it would cost to rebuild your business property, not just its current market value.
Construction materials and labor costs change over time. Ask your agent for an updated Rebuild Cost Assessment to make sure your building coverage limit is realistic.
9. What Has Changed in Your Renewal Documents?
Never assume your renewed policy is identical to the previous one.
Review the declarations page, exclusions, endorsements, limits, and conditions. Pay attention to reduced coverage, higher deductibles, new restrictions, and changes to claim reporting requirements.
Ask your agent to explain any significant changes before renewing.
How to Prepare for the Insurance Renewal Process
Before contacting your agent:
- Review your existing policy and previous claims.
- Update property and equipment values.
- List changes in employees and business operations.
- Identify new risks, including cyber threats.
- Compare premiums and coverage options.
- Request explanations of policy changes in writing.
Start early rather than waiting until your policy is about to expire.
Conclusion:
Business insurance renewal is a chance to make sure your coverage still matches your company’s needs. A lower premium isn’t always better if it means reduced protection or higher deductibles.
Ask about exclusions, liability limits, cyber risks, rebuilding costs, and premium increases. A careful review can help prevent coverage gaps and unexpected expenses.
Frequently Asked Questions
What should I check before insurance renewal?
Review coverage limits, deductibles, exclusions, premium changes, property values, and changes in your business operations.
When should I start the insurance renewal process?
Start several weeks before your policy expires so you have time to compare options and address coverage gaps.
Why did my business insurance premium increase?
Inflation, claims trends, industry risks, insurer pricing changes, and business updates can all affect premiums.
How can I lower business insurance costs?
Compare quotes, improve workplace safety, ask about discounts, and review unnecessary coverage.
Does commercial insurance cover cyberattacks?
Not always. Cyber liability coverage may need to be purchased separately or added through an endorsement.
What is Employment Practices Liability Insurance?
It helps protect businesses against certain employee-related claims, including discrimination, harassment, and wrongful termination.
Is professional liability insurance the same as cyber liability insurance?
No. Professional liability covers certain claims related to professional services, while cyber liability addresses specified cyber incidents and data-related losses.
What is an insurance deductible?
It is the amount your business pays toward a covered claim before the insurer pays its portion.
Why is a rebuild cost assessment important?
It estimates the cost of reconstructing your property and helps ensure your building coverage is sufficient.
Can I switch insurance companies at renewal?
Yes. Compare other providers, but make sure your new policy starts before your existing coverage ends.